




The Dutch state pension age (AOW-leeftijd) is rising to 67 years and 3 months from 2028. If you're a freelancer, expat, or just planning ahead, this guide explains exactly what's changing, how it affects your taxes, and what steps to take now.
What Is AOW, Exactly?
The AOW (Algemene Ouderdomswet) is the Dutch state pension - a basic monthly income provided by the government once you reach the official retirement age. Everyone who has lived or worked in the Netherlands builds up AOW rights, including expats.
Think of it as the foundation of your retirement income, on top of which any employer pension or private savings come into play. If this is your first time hearing about AOW, that's completely normal - especially if you recently moved to the Netherlands.
When Does the AOW Age Go Up?
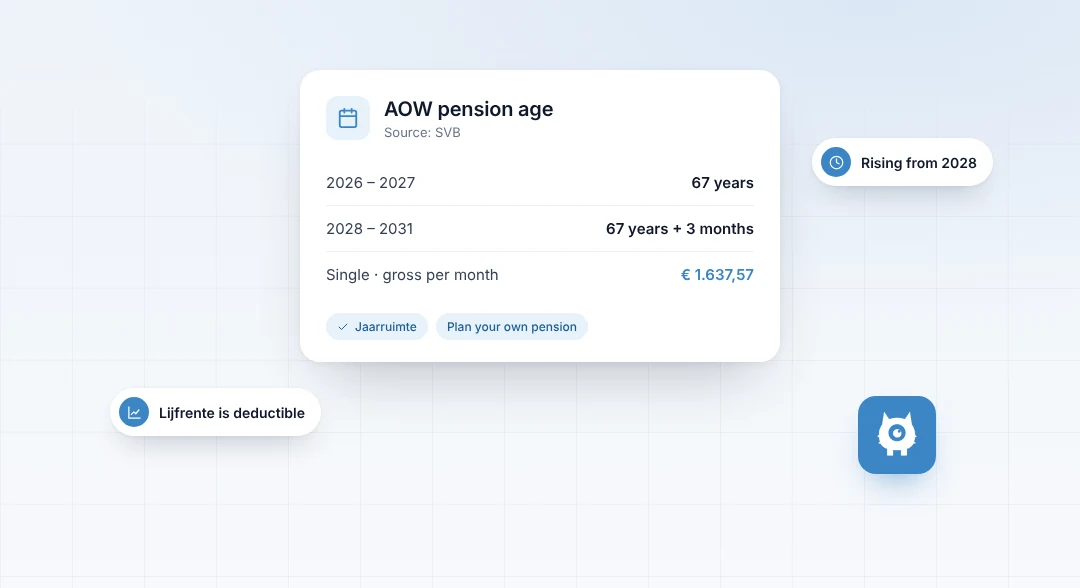
Right now, in 2026, the AOW age sits at 67 years. That’s been the case since 2025 and will remain so through 2027. But starting in 2028, the pension age rises to 67 years and 3 months - and it stays there through 2031.
After 2031, the age will continue to adjust based on life expectancy data published each year by Statistics Netherlands (CBS). The rule: for every additional year of life expectancy, the AOW age goes up by eight months.
- 2025: 67 years (confirmed)
- 2026: 67 years (current)
- 2027: 67 years (confirmed)
- 2028: 67 years + 3 months (confirmed)
- 2029: 67 years + 3 months (confirmed)
- 2030: 67 years + 3 months (confirmed)
- 2031: 67 years + 3 months (confirmed)
How Does This Affect Your Taxes?
Once you reach the AOW age, you stop paying AOW premiums. That means your income tax rate on the first bracket drops significantly. In 2026, people below the AOW age pay 35.75% on income up to €38,883 - but once you’ve reached 67, that rate drops because the AOW premium component falls away.
A later AOW age means you’ll be paying the higher premium-inclusive rate for a bit longer. It’s not a dramatic shift, but over a few extra months it does add up.
Expats, take note: If you’ve lived outside the Netherlands for part of your working life, you may have gaps in your AOW. Each year you weren’t insured means roughly a 2% reduction in your AOW benefit. Taxmo can help you understand the impact on your overall tax picture.

Why ZZP’ers Can’t Rely on AOW Alone
No employer pension? Plan now.
Unlike employees, freelancers in the Netherlands have no employer building a pension for them. The state pension alone - €1.637,57 gross per month for a single person - is unlikely to maintain your lifestyle in retirement.
As a ZZP’er, it’s up to you to construct your own supplementary pension:
- Jaarruimte & Reserveringsruimte - Tax-deductible pension contributions via a lijfrente (annuity). These reduce your taxable income now and pay out at retirement.
- Banksparen - A savings or investment product earmarked for retirement, also tax-deductible.
- Private investments - ETFs, index funds, or real estate to build long-term wealth outside the pension system.
- Voluntary pension funds - Some sector-specific or independent pension providers accept ZZP’ers.
If you haven't started planning yet, don't panic - most freelancers deal with this at some point. The important thing is to start. With the AOW age rising, the gap between stopping work and receiving state pension may grow - making your own pension construction even more critical. Check with a financial advisor (financieel adviseur) for personalized advice. Taxmo automatically calculates your jaarruimte so you know exactly how much you can deduct each year.
How Much Is the AOW Pension in 2026?
As of January 1, 2026, the official monthly AOW amounts according to the SVB are:
- Single person: Gross / month: €1.637,57; Net / month: €1.558,15; Holiday allowance: €106,55
- Married / cohabiting (per person): Gross / month: €1.122,12; Net / month: €1.067,70; Holiday allowance: €76,10
Net amounts include the loonheffingskorting (payroll tax credit). Holiday allowance is paid out once a year in May. Amounts are adjusted every six months in line with the minimum wage. Source: SVB (svb.nl)
What Should You Do Now?
- Check your personal AOW age - use the SVB calculator at svb.nl with your date of birth.
- Review your AOW gaps - especially relevant if you’ve lived abroad. You can voluntarily insure yourself to fill gaps.
- Understand the tax shift - know how your tax rate changes once you hit the AOW age, and plan income timing accordingly.
- File accurately - whether you’re pre- or post-AOW, Taxmo handles the right tax brackets and deductions for your situation automatically.


